A medical emergency abroad can become more serious when the right treatment is not available locally. An evacuation benefit review helps you assess whether an international health insurance plan can arrange and fund transport to an appropriate medical facility, rather than leaving your family to manage a complex and costly situation alone.
For expatriates, frequent travellers and internationally mobile families, this benefit can be one of the most valuable parts of private medical cover. It is also one of the most misunderstood. Medical evacuation is not simply a flight home on request. It is a clinically managed service, usually activated when your condition requires treatment that cannot reasonably be provided where you are.
What does a medical evacuation benefit cover?
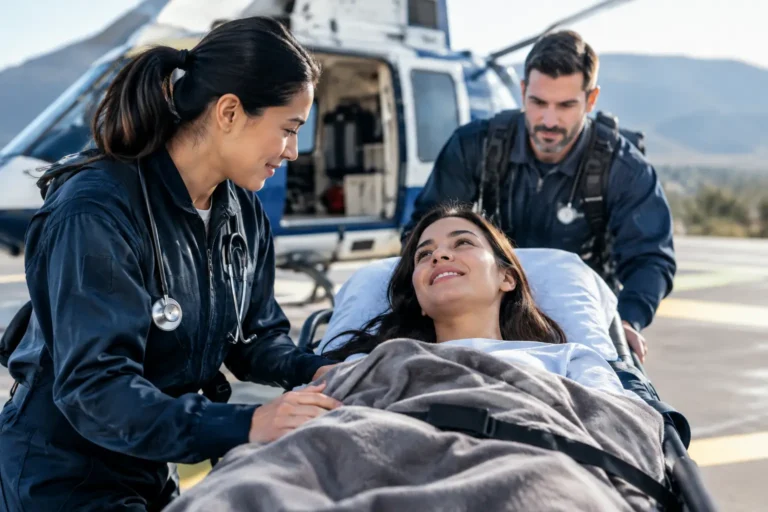
Medical evacuation cover is designed for situations where suitable care is unavailable or inadequate at your current location. Subject to the policy terms and clinical approval, an insurer may arrange transport to the nearest appropriate centre of treatment. This could involve a ground ambulance, commercial flight with medical support, or an air ambulance for severe or time-sensitive cases.
The destination is not automatically your home country, preferred hospital or usual doctor. It will generally be the location judged medically appropriate for the treatment you need, taking account of your stability to travel and the availability of suitable facilities. For someone based in South East Asia, that might mean transfer to a specialist hospital in the region rather than an immediate return to the UK or Canada.
A high-quality international policy may also cover reasonable travel costs for an accompanying person where medically necessary, as well as transport following treatment when this is clinically required. The detail matters: benefits, limits and eligibility vary significantly between plans.
Why an evacuation benefit review matters
The price of a medically supported transfer can be substantial. A short regional air ambulance transfer may cost many thousands of pounds, while a long-haul evacuation with a medical team can be considerably more. More importantly, arranging the transfer requires clinical co-ordination, hospital acceptance, aviation logistics and continuous communication at a stressful time.
A strong international insurer has access to medical assistance teams that assess the case, speak with treating doctors and organise the transfer. That support is as important as the financial benefit. In a serious emergency, families should not need to negotiate with hospitals, source specialist transport or make high-pressure decisions without expert guidance.
An evacuation benefit review is therefore about more than checking a headline limit. It should establish whether your cover is built around genuine access to appropriate care when local facilities cannot meet your needs.
Evacuation and repatriation are different benefits
These terms are often used interchangeably, but they serve different purposes. Medical evacuation moves you to a suitable treatment facility when necessary care is not locally available. Repatriation usually means returning you to your country of nationality or residence, often after treatment or when ongoing care is needed closer to home.
Some plans include both benefits, while others offer evacuation only or apply different limits and conditions to each. If maintaining treatment near family or in your established healthcare system is important to you, ask specifically how repatriation is handled. Do not assume that emergency transport abroad means an automatic flight home.
The questions to ask during an evacuation benefit review
Start with the geographical scope. Worldwide cover can sound comprehensive, but some policies exclude treatment in certain countries, particularly the USA, unless that option has been selected. Check where evacuation can take place from and where the insurer may transfer you to for treatment.
Next, consider the financial structure. Is there a separate evacuation limit, or does the cost count towards the overall annual plan limit? A large annual limit can provide reassurance, but it is still worth confirming whether emergency transport, accompanying persons and post-evacuation care are included within it.
You should also ask how the insurer decides that evacuation is necessary. Policies commonly require the treating medical team and the insurer’s medical advisers to agree that appropriate treatment is unavailable locally. This protects members from unsafe or unnecessary travel, but it means the benefit is based on clinical need rather than personal preference.
Finally, understand the assistance process. In an emergency, you or someone acting for you should contact the insurer’s emergency assistance team as soon as possible. Prior approval is normally required for planned transfers, except where immediate action is needed to protect life. Arranging transport independently without approval may create avoidable problems with reimbursement.
What may not be covered
Premium international cover can offer broad protection, but no policy is unlimited. A clear understanding of exclusions and conditions is essential before you need to rely on the benefit.
Evacuation may not apply where adequate treatment is available locally, even if you would prefer treatment elsewhere. It may also be restricted for conditions excluded under your policy, treatment connected with non-covered services, or claims arising during a waiting period. Pre-existing conditions require particular attention: depending on underwriting, they may be covered, excluded, or accepted with specific terms.
Routine travel home, transport for convenience and non-medical upgrades are generally outside the purpose of medical evacuation cover. The same applies where a member declines a clinically appropriate local treatment option without a compelling medical reason.
For business leaders arranging cover for employees, it is worth considering the practical implications of these restrictions. A regional workforce may travel to remote sites, work offshore or spend time in countries with limited specialist facilities. The right plan should reflect those real-world exposure points, not simply the employee’s main residential address.
Matching the benefit to your lifestyle
The right level of evacuation protection depends on where you live, where you travel and how you want care decisions to be managed. A family living in Singapore with regular holidays and business travel across Asia may have different priorities from an executive posted to a developing market, or a Canadian resident working between Europe and the Middle East.
Consider your nearest realistic centres of specialist care. For complex cardiac, neurological, neonatal or trauma treatment, proximity to a well-equipped hospital can make a material difference. If you spend time in locations with limited emergency infrastructure, comprehensive evacuation cover deserves closer attention than a minor add-on to your plan.
It is also sensible to consider who may travel with you. A medical emergency involving a child, partner or elderly parent places a different burden on a family. Policies differ on the support available for companions, dependent children left unattended and travel expenses connected with an evacuation. These are practical details, but they can be decisive when an emergency occurs far from home.
How international health insurance supports the process
International private medical insurance is intended to provide continuity when your life crosses borders. Alongside inpatient treatment, specialist access and high annual limits, evacuation cover can help bridge the gap between a local emergency and the standard of care you need.
Bupa Global plans can be considered by customers seeking premium international healthcare solutions, subject to the level of cover selected and applicable policy terms. The most suitable option should be based on your destinations, medical history, family circumstances and appetite for worldwide protection.
A professional adviser can help you compare the practical wording behind each plan, including evacuation triggers, territorial limits, repatriation provisions and the treatment of pre-existing conditions. This is especially useful when comparing policies that appear similar on price but differ in the support available during a major medical event.
Arrange cover before an emergency tests it
Medical evacuation is a benefit you hope never to use, yet it can shape the outcome of a serious illness or injury overseas. Before choosing international health insurance, review the policy wording carefully and ensure your adviser understands where you live, travel and receive care.
The right protection gives you more than a route out of an emergency. It gives you the confidence that experienced medical professionals can help direct you towards appropriate treatment, wherever your life takes you.