A medical emergency abroad can become more complicated when the local hospital cannot provide the specialist treatment you need. Knowing how to arrange medical evacuation before a crisis occurs can protect both your health and your finances, particularly if you live, work or travel across borders.
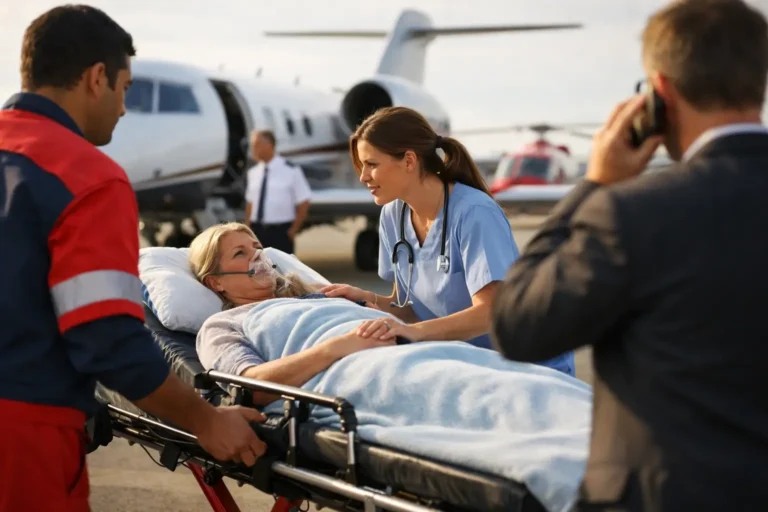
Medical evacuation is not simply booking the next available flight home. It is a carefully managed clinical transfer, arranged when a treating doctor and assistance team agree that appropriate care is unavailable locally or that transfer is medically necessary. The journey may involve a commercial flight with a medical escort, a ground ambulance or, in more serious cases, an air ambulance with intensive-care capability.
Start with the local emergency response
If there is an immediate threat to life, call the local emergency services or go to the nearest appropriate emergency department. Do not delay urgent treatment while trying to contact your insurer. The priority is stabilisation by qualified clinicians.
Once the patient is safe to speak with an assistance provider, or a family member can act on their behalf, contact the emergency assistance number shown on the health insurance membership card. A premium international medical policy may provide round-the-clock support to coordinate care, verify cover and speak directly with the hospital.
Have the patient’s full name, policy number, current location, treating hospital, diagnosis or suspected condition, and the doctor’s contact details ready. It is also useful to provide the names and telephone numbers of close family members who can authorise information sharing where necessary.
How to arrange medical evacuation through your insurer
The insurer’s medical assistance team will assess whether evacuation is covered and clinically appropriate. This is not a decision made by the patient alone, nor is it normally a service that should be privately arranged without approval. Unapproved transport can leave you responsible for a very substantial bill and may put the patient at avoidable risk.
The process usually begins with a discussion between the assistance team and the treating doctor. They will review the patient’s condition, the facilities available locally, the treatment required and whether the patient is stable enough to travel. If specialist treatment is needed, the team may also identify a suitable receiving hospital in the country of residence, a regional medical centre or another location with the necessary expertise.
Clinical necessity comes first
Medical evacuation benefits are generally designed for situations where adequate treatment is not available locally, rather than for personal preference. For example, a patient with a complex neurological injury on a remote island may need transfer to a regional specialist centre. By contrast, an uncomplicated condition that can be treated safely at the local hospital may not meet the criteria for evacuation.
The safest destination is not always the patient’s home country. It may be the nearest location with the right specialist, equipment and bed availability. This can be difficult for families to hear, especially when they want to return home immediately, but the clinical recommendation should guide the decision.
The assistance team coordinates the journey
Once authorised, the assistance provider typically manages the practical arrangements. This may include confirming the receiving hospital, obtaining medical reports, arranging transport to and from airports, securing airline medical clearance and selecting the appropriate level of medical escort.
For a stable patient, a scheduled airline flight with a nurse, paramedic or doctor may be suitable. A stretcher, supplementary oxygen or extra seating may be required. Where the patient needs continuous monitoring, ventilation or urgent specialist support, an air ambulance may be necessary. The choice depends on clinical need, distance, weather, airport access and the patient’s condition – not simply on convenience.
The team may also help obtain travel documents, coordinate with consular services where appropriate and keep family members updated. Exact support varies by policy and circumstance, so always ask what is included before arrangements are confirmed.
What information and documents will be needed
A well-managed evacuation depends on accurate information moving quickly between clinicians, the insurer and the receiving facility. The hospital will normally supply a medical report covering the diagnosis, treatment given, current observations, medication, mobility and fitness to travel.
The assistance team may request imaging results, laboratory reports, copies of identification and insurance details. They will also need confirmation that the receiving hospital has accepted the patient. Where a patient cannot make decisions, consent may need to come from a legally authorised representative, subject to local law and the patient’s medical circumstances.
Keep copies of receipts, reports and contact names where possible. In an emergency, however, do not attempt to manage the clinical logistics yourself. Your role is to provide clear information, stay reachable and make sure the assistance team can communicate with the treating doctors.
Understand what your policy may cover
International private medical insurance can offer valuable protection for medically necessary evacuation, but cover is defined by the policy terms. Check whether evacuation is included, the geographical area of cover, any annual limits, exclusions and whether repatriation is treated separately from evacuation.
Evacuation generally means transferring a patient to the nearest suitable treatment facility. Repatriation may refer to returning the patient to their home country after treatment, or returning mortal remains in the event of death. Some policies include both benefits; others apply different conditions. A policy may also cover reasonable travel for a companion, but this is not automatic and often depends on the patient’s age and medical condition.
Pre-existing conditions, policy waiting periods, travel to excluded territories and treatment arising from high-risk activities can affect eligibility. It is worth reviewing these details while you are well, rather than discovering limitations during a medical crisis.
For internationally mobile families and businesses, broad geographic cover and a high level of evacuation protection can be particularly valuable. A serious illness in a location with limited private healthcare infrastructure can lead to transport costs that far exceed ordinary medical bills. Bupa Global plans are designed for members who value access to international treatment and coordinated support when local care is not enough.
Avoid common and costly mistakes
The first mistake is waiting too long to notify the insurer. Early contact allows the assistance team to advise the hospital, review options and prepare a transfer if it becomes necessary. It can also prevent a family from paying for transport that the insurer would not have approved.
The second is insisting on a destination before the medical assessment is complete. A particular city or hospital may be preferred, but bed availability, specialist capability and flight safety may point elsewhere. Ask for the reasoning behind the recommendation and raise any concerns, while allowing the clinical team to lead.
The third is assuming a travel insurance policy offers the same protection as comprehensive international health insurance. Emergency cover can vary significantly in its limits, exclusions and ability to support planned onward treatment. If you spend substantial time abroad, have ongoing healthcare needs or travel with children, it is sensible to assess the quality of medical evacuation benefits in advance.
Prepare before you travel or relocate
A little preparation makes a difficult event more manageable. Save the insurer’s emergency number in your mobile phone and share it with your partner, adult children or travel manager. Keep a digital copy of your membership card, passport, current prescriptions, allergies and relevant medical history in a secure place.
If you have a chronic condition, speak with your doctor before travelling and carry a concise clinical summary. Confirm that your destination falls within your policy’s area of cover and ask whether any planned activities require additional protection. Businesses should also ensure employees on overseas assignments understand whom to contact and how to access their insurance information.
When urgent treatment is required far from home, calm, early communication is one of the most useful things you can provide. Seek local emergency care first, contact your medical assistance provider as soon as possible, and let qualified clinicians coordinate the safest route to the right treatment.