A serious illness or injury abroad can create a decision no family wants to make under pressure: stay where you are, or move quickly to a hospital better equipped to provide the treatment you need. Understanding how medical evacuation cover works helps internationally mobile people plan for that possibility before an emergency turns into a financial and logistical crisis.
Medical evacuation cover is designed to arrange and fund medically necessary transport when appropriate treatment is not available locally. It is not simply a flight home. The decision is based on your clinical condition, the facilities available where you are and the advice of the insurer’s medical team. For expatriates, frequent travellers and families living between countries, this support can be one of the most valuable features within a premium international health insurance plan.
What medical evacuation cover is designed to do
Medical evacuation cover steps in when a doctor determines that you need treatment which cannot be provided safely or adequately at your current location. The insurer’s assistance team then co-ordinates transport to the nearest suitable medical facility able to deliver that care.
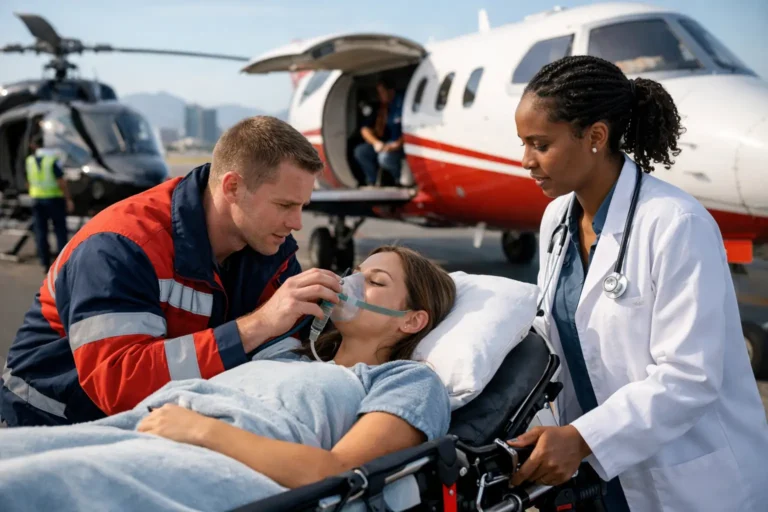
Depending on the circumstances, this could mean a ground ambulance to a better hospital in the same country, a commercial flight with a medical escort, or an air ambulance with specialist equipment and clinicians on board. The level of transport is selected according to medical need, not personal preference.
For example, an expatriate on a remote Indonesian island may require surgery only available in Singapore. A family member admitted to a smaller hospital while travelling may need transfer to a regional centre with a neurological unit. In each case, evacuation cover is intended to remove the burden of finding transport, securing clinical acceptance and meeting potentially substantial costs at a difficult time.
How medical evacuation cover works in an emergency
The process usually begins with a call to the insurer’s emergency assistance service as soon as possible. If immediate treatment is required, seek urgent local medical attention first. Once the assistance team is notified, it will liaise with the treating doctors and review the medical information.
A medical assessment comes first
The insurer’s clinical team will assess whether evacuation is medically necessary. They consider the diagnosis, the patient’s stability for transport, the quality and availability of local treatment, and whether a suitable receiving hospital can accept the patient.
This is why evacuation cover should not be confused with a guaranteed return to your preferred hospital or country of residence. If appropriate care is available nearby, the plan may authorise treatment there rather than arrange an international transfer. Equally, a patient who is too unwell to travel may first need stabilising treatment locally.
The assistance team co-ordinates the journey
When an evacuation is approved, the assistance provider manages the practical details. This can include speaking with doctors, arranging the receiving hospital, organising the ambulance or aircraft, obtaining travel clearances and providing a medical escort where required.
This co-ordination matters as much as the funding. A cross-border transfer may involve medical reports, airline requirements, equipment, visas, airport ambulance access and hospital admission arrangements. Families should not have to organise these details alone while supporting someone who is seriously unwell.
Costs are paid within the plan terms
Approved evacuation costs are generally covered under the terms and limits of your policy. These costs can be considerable, particularly where an air ambulance, specialist crew or long-distance transfer is required. The exact benefit depends on the plan selected, its geographical area of cover, annual limits and any applicable exclusions.
Premium international health insurance is built for situations where access to quality care matters more than being limited to a local system. However, cover is never identical across all policies. Reviewing the evacuation benefit before you buy is essential.
Evacuation, repatriation and routine travel insurance are not the same
These terms are often used together, but they serve different purposes. Medical evacuation means transport to the nearest appropriate treatment centre when necessary care is unavailable locally. The priority is getting the patient to suitable clinical treatment.
Repatriation usually refers to returning a patient to their home country or country of residence after treatment, or sometimes returning mortal remains following death. Some international health insurance plans include repatriation benefits, while others structure them differently. The detail matters if staying close to home during recovery is a priority for you and your family.
Travel insurance may include emergency medical transport, but it is generally intended for shorter trips and may have lower benefit limits, narrower eligibility or restrictions for pre-existing conditions. It should not automatically be seen as a replacement for comprehensive international private medical insurance, particularly for people living overseas, relocating frequently or seeking ongoing access to private care.
What may affect whether evacuation is approved
Medical evacuation is a clinical benefit, which means approval depends on the circumstances rather than a traveller’s preference alone. It may not be authorised if equivalent treatment is available locally, if the transfer is not medically necessary or if travel would put the patient at greater risk.
Policy terms also matter. Pre-existing conditions may be covered, excluded or accepted with special terms depending on underwriting and the plan. Non-emergency treatment, elective transfers and movement arranged without contacting the assistance team may not be eligible for reimbursement. Some plans may also have geographical restrictions or require that transport is to the nearest suitable centre rather than a hospital chosen by the member.
There are practical trade-offs too. The closest suitable hospital may be in a neighbouring country rather than your home country. Your insurer’s medical team will focus first on safe treatment and appropriate facilities. This can feel challenging when family, language and familiarity point elsewhere, but it is often the fastest route to the care required.
Why this benefit matters for globally mobile families and businesses
For people based in Singapore, South East Asia or other international locations, healthcare quality can vary significantly between cities, islands and regions. Living abroad does not always mean living near a tertiary hospital with specialist intensive care, trauma, cardiac or paediatric services.
Medical evacuation cover provides a defined pathway when local capability is not enough. It gives individuals and families confidence that an experienced assistance team can make clinical and transport arrangements across borders, rather than leaving them dependent on local contacts or last-minute fundraising.
For employers, it is also a meaningful part of duty of care. Employees posted to remote sites, emerging markets or multiple countries need more than a local medical policy. A suitable international plan can support continuity of care and demonstrate that the business has considered serious medical events, not only routine consultations.
Choosing medical evacuation cover within an international plan
When comparing international health insurance, look beyond the headline that says “evacuation included”. Ask where the patient can be transported, whether repatriation is available, how the assistance service operates and whether evacuation costs sit inside or outside the overall annual limit.
It is also sensible to consider your real pattern of life. A professional who lives in Singapore but spends months working across the region may have different needs from a family based in a major city with regular holidays in remote areas. Existing health conditions, children’s healthcare needs, destinations and access to nearby specialist hospitals all influence which level of cover is appropriate.
Bupa Global plans are designed to offer internationally mobile members access to high-quality healthcare and support beyond their country of residence. The right option should be based on your location, budget, medical history and the level of global protection you expect.
Be prepared before you need assistance
Keep your membership details and emergency assistance number accessible to your partner, adult children or trusted colleague. If you travel regularly, save the number on your mobile phone and carry it separately from your wallet. In a severe emergency, someone else may need to make the call.
Before committing to any plan, ask for a clear explanation of evacuation and repatriation benefits in writing. The greatest value of medical evacuation cover is not merely the transport itself. It is the assurance that, if local care is not enough, experienced people are ready to help move you towards the treatment you need.