A serious illness or injury abroad creates decisions that cannot wait for the next available commercial flight. Understanding medical evacuation versus repatriation cover helps internationally mobile families, employees and frequent travellers assess whether their health insurance can arrange the right care in the right location – and meet the substantial cost of getting there.
The two benefits are often discussed together, but they protect against different circumstances. Medical evacuation is primarily about reaching appropriate treatment when it is not available locally. Repatriation is about returning home, or to a chosen country of residence, after a medical event. The distinction matters when comparing premium international health insurance.
What medical evacuation cover means
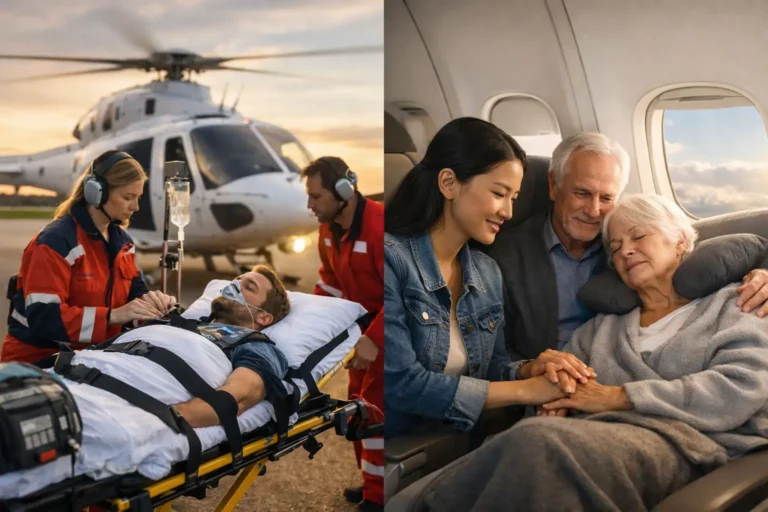
Medical evacuation cover funds and co-ordinates transport to the nearest suitable medical facility when the required treatment cannot be provided safely where you are. This may involve a road ambulance, air ambulance, medically equipped commercial flight, or another clinically appropriate method of transport.
The decision is normally based on medical necessity, not personal preference. If a local hospital can provide the treatment you need to an appropriate standard, an insurer may not approve evacuation simply because you would rather receive care elsewhere. However, if specialist surgery, intensive care or equipment is unavailable, evacuation can be the difference between delayed treatment and prompt access to a suitable hospital.
For someone living in a regional location in South East Asia, this might mean transfer to a leading hospital in Singapore, Bangkok or another nearby medical hub. For a family travelling internationally, it could mean transport to the closest centre with the required specialist expertise. The destination is determined by clinical need, availability and safety.
A well-designed international private medical insurance plan should also provide access to an assistance team that can assess the case, speak with treating clinicians and organise transport. In an emergency, arranging an air ambulance independently is not a realistic or desirable burden for a patient or their family.
What repatriation cover means
Repatriation cover concerns the journey back to your home country or country of residence after illness, injury or, in some policies, death. It may include a medically supervised return once you are stable enough to travel, as well as necessary arrangements for the return of mortal remains where this is covered.
Unlike medical evacuation, repatriation does not always require a lack of local treatment. A person may have received appropriate emergency care abroad but need continuing recovery, rehabilitation or support closer to home. The policy terms will define when a return journey is covered and whether it must be medically necessary.
This benefit can be particularly valuable for expatriates whose support network is spread across countries. A partner may be working in Singapore while parents and long-term medical specialists are in the UK or Canada. Returning to familiar surroundings can be deeply reassuring, but insurance cover is governed by the plan rules, medical advice and practical safety considerations.
Medical evacuation versus repatriation cover: the key difference
The simplest distinction is purpose. Medical evacuation gets you to appropriate treatment. Repatriation gets you back home or to your country of residence after treatment or stabilisation.
That difference affects the destination, timing and approval criteria. An evacuation may take place immediately because advanced treatment is unavailable locally. Repatriation may happen later, once clinicians confirm that travel is safe. In some cases, both benefits may be relevant: a patient is first evacuated to a specialist hospital, then repatriated after recovery or once they can continue treatment nearer home.
Neither benefit should be treated as an automatic private flight home. Insurers generally require prior authorisation except where circumstances make this impossible, and their medical teams will select safe, reasonable transport arrangements. This protects the patient and helps ensure that a major claim is managed with clinical oversight.
Why travel insurance may not be enough
Travel insurance can include emergency medical evacuation and repatriation, but it is usually designed for short trips. It may not provide the breadth of inpatient, outpatient, specialist and long-term treatment cover required by someone who lives overseas or divides their time between countries.
International health insurance is built for a different need: continuity of private healthcare across borders. It can support planned treatment as well as unexpected emergencies, subject to the chosen area of cover, benefits and policy terms. For globally mobile individuals, this is often more relevant than relying solely on a travel policy that expires when the holiday or business trip ends.
There are trade-offs. A comprehensive international plan may cost more than basic travel cover, particularly where worldwide protection including the United States is selected. Yet the value lies in access to private hospitals, specialists and medical support when local arrangements are unfamiliar or inadequate. For a family with international schooling, overseas assignments or multiple residences, that certainty can be worth far more than a low premium.
What to check before choosing cover
The headline phrase “evacuation and repatriation included” is reassuring, but the detail determines how useful the benefit will be. Read the policy wording and ask clear questions before you need to claim.
Pay close attention to the geographical area of cover. A plan may provide worldwide treatment, or it may exclude the United States unless that option is selected. You should also confirm whether evacuation is to the nearest appropriate facility, a regional treatment centre, or another destination permitted under the policy.
Check the annual benefit limits and whether evacuation and repatriation are paid in full or sit within an overall policy maximum. Premium plans often offer high annual limits, but benefits and exclusions differ. Pre-existing conditions, waiting periods, hazardous activities and treatment related to excluded conditions may all affect eligibility.
It is also sensible to ask about accompanying family members. If a child is evacuated, can a parent travel with them? If you are hospitalised overseas, does the plan contribute towards a companion’s transport or accommodation? These practical provisions can matter as much as the transport itself when a family is far from home.
Finally, understand the claims process. Keep the insurer’s emergency assistance number readily available, preferably saved in your mobile phone and shared with your partner or employer. In a medical emergency, contact the assistance team as soon as possible. They can liaise with hospitals, confirm cover and co-ordinate a transfer without leaving relatives to negotiate complex arrangements alone.
Who benefits most from international protection
Medical evacuation and repatriation benefits are particularly relevant to expatriates based outside major medical centres, families who travel frequently, senior executives on overseas assignments and businesses responsible for employee welfare across several countries. They are also worth considering for people who want the option of private specialist care rather than relying solely on local public provision.
For employers, these benefits form part of a credible duty-of-care approach. An employee taken seriously ill during an overseas posting needs more than a reimbursement promise. They need a clear route to appropriate treatment, professional case management and support for their family.
For individuals, the question is less about expecting the worst and more about removing uncertainty. A sudden diagnosis abroad should not force you to decide between unaffordable transport, an unfamiliar facility without the necessary expertise, or separation from those who can support you.
Bupa Global international health plans are designed for people who expect high-quality healthcare wherever life takes them, with plan options that can be tailored around location, lifestyle and family needs.
Choose cover for the life you actually lead
The right protection depends on where you live, how often you travel, the quality of nearby healthcare and the level of choice you want if serious treatment is needed. Someone based permanently in a city with excellent private hospitals may prioritise broad local and regional specialist access. Someone working across remote locations may place greater value on extensive evacuation arrangements.
Before buying, consider the places you call home, the countries you visit regularly and who would need to be beside you if an emergency occurred. A tailored international health insurance recommendation can then turn medical evacuation and repatriation from unfamiliar policy language into practical reassurance when it matters most.