A serious illness or injury abroad creates decisions that cannot wait for the next available commercial flight. The best medical evacuation benefits provide access to clinical expertise, transport arrangements and financial protection when suitable treatment is unavailable locally. For expatriates, internationally mobile families and businesses with employees across borders, this support can be one of the most valuable parts of a premium international health insurance plan.
Medical evacuation is not simply a flight home. It is a clinically managed process designed to move a patient safely to the nearest appropriate treatment facility, whether that is in another city, a neighbouring country or their country of residence. The quality of the benefit lies in the detail: who decides evacuation is necessary, where the patient is taken, how transport is arranged, and what support is available before, during and after the journey.
What medical evacuation cover is designed to do
A medical evacuation benefit applies when a patient needs treatment that cannot be provided safely or appropriately at their current location. This may arise in a remote area with limited hospital facilities, or in a major city where specialist care for a complex condition is not available.
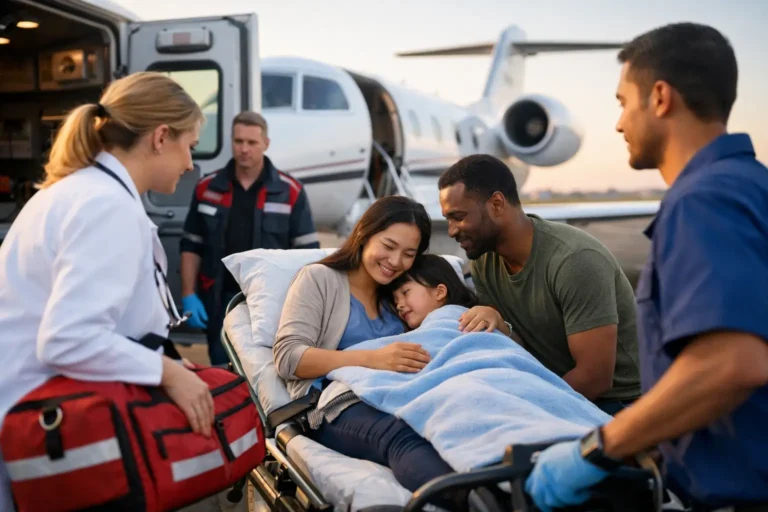
The insurer’s medical team will usually review the patient’s condition with the treating doctors. If evacuation is clinically necessary and covered by the policy, they coordinate the transfer to an appropriate medical centre. Depending on the medical need, this could involve a commercial flight with a medical escort, a dedicated air ambulance, ground ambulance transfers, or a combination of these arrangements.
This distinction matters. A premium policy is intended to arrange clinically appropriate care, not to provide transport based on personal preference alone. If a capable local facility is available, evacuation may not be authorised. Equally, if local care is inadequate for the condition, a strong evacuation benefit can prevent financial considerations from delaying a vital transfer.
The best medical evacuation benefits to look for
The strongest benefits combine high-value transport cover with expert clinical coordination. When comparing international private medical insurance, look beyond a headline that simply says “emergency evacuation included”. The policy wording and service model determine the practical value when an emergency occurs.
Clinical decision-making and 24-hour assistance
A trusted emergency assistance service is central to effective evacuation cover. The service should be available around the clock and staffed by medical professionals who can speak with local doctors, assess the treatment options and monitor the patient’s condition.
This clinical oversight protects the patient as well as the family. In a stressful situation, relatives should not have to research hospitals, negotiate with transport providers or decide whether a patient is fit to fly. An experienced medical team can make those arrangements and remain involved as circumstances change.
Transfer to the nearest appropriate centre of treatment
The phrase “nearest appropriate” is one of the most significant in any policy. It means the destination should be selected for its ability to provide the required level of care, rather than simply being the closest hospital or the patient’s preferred location.
For example, a traveller who develops a serious neurological condition while staying on an island may need transfer to a regional specialist hospital. A patient with a severe trauma injury may require a facility with advanced surgical, intensive care and rehabilitation capability. This approach helps ensure that the evacuation is connected to a meaningful treatment plan.
Air ambulance and medically escorted travel where needed
Not every evacuation requires an air ambulance, and not every patient can travel on a scheduled flight. The transport method should reflect the patient’s medical condition. A stable patient may travel with a nurse or doctor on a commercial aircraft, while a critical patient may need a dedicated aircraft with intensive-care equipment and a specialist medical crew.
Air ambulance costs can be substantial, particularly for long-distance transfers across South-East Asia, Europe, North America or Australia. Adequate cover for medically necessary transport is therefore essential for people whose work, residence or holidays regularly take them outside their home healthcare system.
Ground transport and transfer coordination
Evacuation support should not end at the airport. A well-managed case includes ambulance transfers from the original hospital to the airport, from the destination airport to the receiving hospital, and any necessary arrangements between medical facilities.
These details are easy to overlook when comparing policies, but they are vital in practice. Coordinated handovers reduce avoidable delays and give the receiving care team the information needed to prepare for the patient’s arrival.
Travel and accommodation support for a companion
When a child, older adult or seriously unwell patient is evacuated, a family member may need to travel with them. Some plans include reasonable transport and accommodation costs for a companion, subject to policy terms and medical approval.
This benefit is about more than comfort. A familiar person can help with communication, consent discussions and practical arrangements during a frightening period. Families should confirm who qualifies as a companion, what expenses are covered and whether the benefit applies during hospitalisation as well as travel.
Repatriation after treatment
Medical evacuation and repatriation are related but different benefits. Evacuation is generally intended to get a patient to suitable treatment. Repatriation concerns the return journey to a home country or country of residence, often after the patient is stable enough to travel.
A plan may cover repatriation in certain circumstances, but the terms can vary considerably. Some policies focus on transport to the nearest appropriate treatment centre, not a preferred hospital in another country. Others may provide additional flexibility for return travel following treatment. This is a useful area to discuss before choosing cover, especially for families who want continuity with doctors in their home country.
When evacuation cover has the greatest value
The benefit is particularly relevant for people based in locations where local private care is excellent for routine treatment but less equipped for highly complex emergencies. It can also be valuable for frequent travellers, senior executives on regional assignments, families living away from their established support network and employers responsible for staff in remote or developing locations.
Consider a family living in Singapore that travels regularly through the region. Most healthcare needs may be handled locally, but an emergency during a holiday in a remote destination could require urgent transfer. Or consider an employee assigned to a country where advanced oncology, neonatal or trauma care is limited. In both cases, an international plan can offer a route to appropriate care without leaving the family or employer to arrange and fund a complex operation independently.
The value also depends on personal circumstances. Someone who remains within one country with strong public and private hospital capacity may place less emphasis on evacuation than a person whose lifestyle spans several continents. A thoughtful insurance recommendation should reflect where you live, where you travel, your family’s health needs and the standard of care you expect to access.
Questions to ask before choosing a plan
Coverage descriptions can sound similar while offering very different protection. Ask whether medical evacuation is included as standard or available only as an optional benefit. Confirm the annual benefit limit, whether pre-authorisation is required and how the insurer defines an appropriate treatment facility.
You should also ask whether there are geographic restrictions, how pre-existing conditions are assessed, and whether companion travel, local ground transfers and repatriation are included. Waiting periods, exclusions and underwriting terms may affect when benefits are available. Clear answers before purchase are far more reassuring than assumptions during an emergency.
For businesses, the questions should extend to employee locations and travel patterns. A plan that suits office-based staff in a major city may not provide the same reassurance for teams working on regional projects, travelling frequently or relocating with dependants.
Pair evacuation cover with the right wider protection
Evacuation cover works best as part of comprehensive international private medical insurance. After transport has been arranged, the patient still needs hospital treatment, specialist consultations, diagnostics, surgery, medicines and follow-up care. A high annual limit and access to quality private facilities help make sure the wider treatment journey is protected too.
Premium international cover can also support continuity when a family moves country or needs access to recognised specialists outside the local market. Bupa Global plans, supported by tailored guidance from Global Medical, can be considered by customers seeking international healthcare cover that reflects a globally mobile lifestyle.
Before committing to a policy, consider how it would work in one realistic scenario: a serious emergency during a work trip, a family holiday or a relocation. If the plan gives you confidence in the clinical decisions, destination options and financial protection involved, it is likely providing the reassurance that global health cover should deliver.